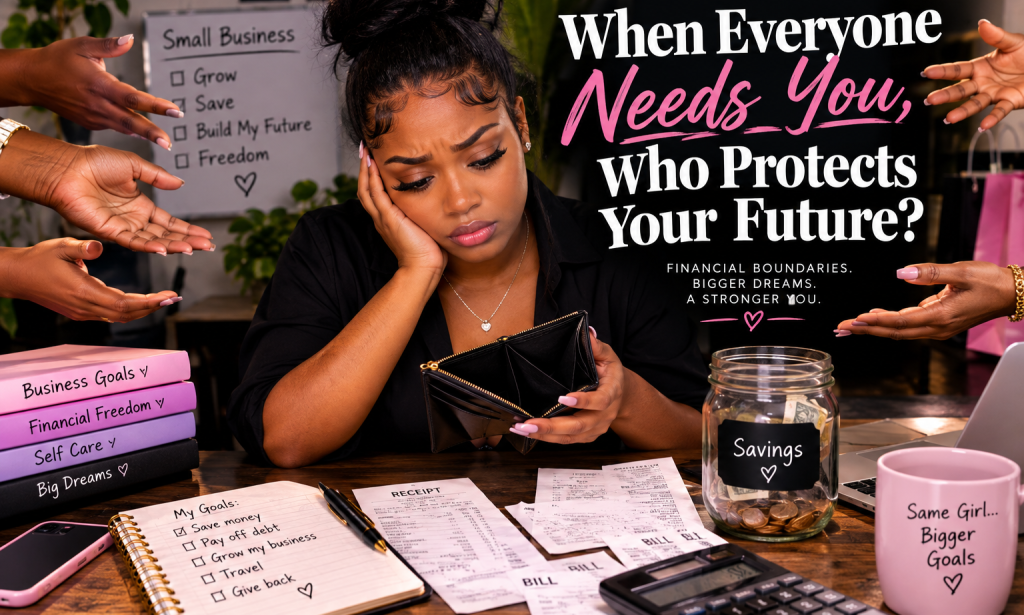
The Hidden Tax of Being Everyone’s Financial Lifeline: Why Helpful People Struggle to Build Wealth
When Being the Reliable One Becomes Expensive
There is a particular kind of financial pressure that rarely appears on a bank statement.
It does not come from a credit card company, a bank loan, or a monthly subscription. Instead, it comes from being the person everyone believes can help.
You may be the relative who gets called when rent is due, the friend who lends money before payday, or the business owner whose earnings become the emergency fund for an entire family.
People trust you because you have helped them before. You may even feel proud that others can depend on you.
But what happens when the person everyone depends on can no longer depend on their own savings?
This is the hidden tax of being financially reliable. It is the money, time, and opportunity you sacrifice when helping others becomes a permanent responsibility rather than a choice.
The Money That Never Gets a Chance to Grow
Imagine a small business owner who earns money every week. After paying business expenses, transportation, supplies, and personal bills, the owner plans to save a portion of the remaining income.
Then the requests begin.
A relative needs money for groceries. A friend needs help with an electricity bill. Someone else promises to repay a small loan next week.
Each request seems manageable on its own.
The problem appears when these requests become a pattern. The savings account never grows because money leaves almost as quickly as it arrives.
The business owner continues working hard but never seems to move forward financially.
This is an important distinction: earning money and building wealth are not the same thing.
Income is money coming in. Wealth building requires keeping some of that income, protecting it, and using it to create future stability.
When every extra dollar becomes available to someone else, hard work can turn into a cycle of earning, giving, and starting over.
The Invisible Cost of Money You Never Invested
Consider a hypothetical example.
Suppose someone could consistently save $5,000 per month in their local currency but instead gives that amount away through repeated, unplanned financial assistance.
Over one year, the total is $60,000.
Over five years, the total would be $300,000, before accounting for inflation, investment returns, or changes in income.
That does not mean helping others is a mistake. It means every financial decision has an opportunity cost.
The money you give away cannot simultaneously pay down your debt, fund your education, purchase equipment for your business, or build your emergency savings.
The most painful part is that these missed opportunities may remain invisible. Nobody sees the business you could have expanded or the financial security you could have built.
They only see the immediate help you provided.
When Your Business Becomes Everybody’s Backup Plan
For entrepreneurs, this problem can become especially serious.
A small business may generate cash, but not all the money in the account is profit. Some of it must cover inventory, supplies, transportation, rent, taxes, equipment, and future operating expenses.
When an entrepreneur mixes business money with family emergencies, the business can appear successful while becoming financially weaker.
For example, a hairstylist may receive payment from several clients and plan to purchase braiding supplies for upcoming appointments. If that money is repeatedly borrowed by relatives, the stylist may have to delay purchases, turn away customers, or use personal funds to cover business expenses.
The original request may have been small, but its consequences can spread.
A missed purchase can mean lost sales. Lost sales can mean reduced income. Reduced income can make the next emergency even harder to manage.
This is why business owners need to understand one crucial principle:
Business revenue is not personal spending money, and business cash is not automatically available for family assistance.
A business needs its own financial boundaries to survive.
Why Saying No Can Feel Like Betrayal
The financial problem is only half the story. The emotional pressure can be even harder.
Some people were raised to believe that sharing what they have is a responsibility. Others fear being called selfish, ungrateful, or arrogant when their financial situation improves.
When you have always been the helper, changing your behavior can surprise the people around you.
A simple statement such as “I cannot afford to help this time” may feel uncomfortable, even when it is the most responsible decision.
You might worry that people will stop loving you, become angry, or assume that you have changed because you now have money.
But financial boundaries do not have to mean abandoning your loved ones.
They mean recognizing that your needs, responsibilities, and future also deserve consideration.
You can care about someone’s circumstances without personally financing every problem they experience.
The Difference Between Generosity and Financial Self-Sabotage
Generosity is most sustainable when it comes from a realistic plan.
Financial self-sabotage begins when helping others repeatedly forces you to neglect your own basic needs, borrow money, miss bill payments, or delay essential business expenses.
Before providing financial assistance, consider three questions.
Can I afford to give this money without borrowing or missing an important payment?
If the answer is no, the assistance may create another financial problem rather than solve one.
Is this a one-time emergency or a repeated pattern?
A genuine emergency deserves compassion. A repeated pattern may require a different conversation about budgeting, income, spending, or other sources of support.
Am I choosing to help, or am I afraid of what will happen if I refuse?
This question helps distinguish generosity from guilt-driven spending.
You do not need to judge anyone to answer these questions honestly.
A Practical System for Helping Without Losing Yourself
The solution is not to become cold or stop caring about people. It is to build a system that allows generosity without sacrificing financial stability.
1. Create a planned assistance budget
Choose an amount you can realistically afford to use for helping others each month. This could be a fixed amount or a percentage of your available income after essential expenses and priority savings.
Once the budget is used, pause additional financial assistance until you can review your finances again.
If your income changes, adjust the amount accordingly.
2. Separate business funds from personal funds
If you own a small business, maintain separate accounts or clearly separated records for business operations and personal spending.
Pay yourself according to a plan that reflects what the business can actually afford. Do not use money reserved for supplies, bills, taxes, or other obligations to cover unrelated requests.
3. Build your own emergency fund
Start with a manageable target and increase it gradually. Even a small reserve can reduce the need to borrow when an unexpected expense appears.
Your emergency fund should protect you from genuine emergencies, not automatically become a shared fund for everyone around you.
4. Learn to offer help without always offering money
Sometimes support can take another form.
You might help someone compare bills, prepare a budget, find employment opportunities, understand a business idea, or locate community resources.
You can be supportive without assuming financial responsibility for the entire situation.
5. Use a pause before agreeing
When someone asks for money, you do not have to answer immediately.
Try saying, “Let me check my budget before I make a decision.”
This gives you time to consider your obligations without allowing guilt or urgency to control the decision.
6. Set repayment expectations before lending
If you choose to lend money, agree on the amount, repayment date, and terms beforehand. Only lend money you can reasonably afford to have tied up, and consider whether you could cope if repayment never happens.
If you cannot afford that risk, a smaller gift within your budget—or declining the request—may be safer.
What Financial Success Should Really Look Like
Imagine a future in which helping your family does not leave you worried about your own bills.
Imagine owning a business that can purchase its supplies on time, pay its obligations, and survive a slower month.
Imagine having savings that remain available when you experience a genuine emergency.
These are not selfish ambitions. They are foundations for sustainable financial independence.
When your own finances are stronger, you may be able to help others more consistently and thoughtfully. But that ability grows from stability, not from repeatedly emptying your pockets.
You are allowed to become financially secure even when the people around you are still struggling.
You are allowed to save money without explaining every dollar.
You are allowed to build a business without treating its income as public property.
And you are allowed to say no without turning that decision into a measure of how much you care.
Final Thoughts: You Cannot Build Everyone’s Future While Abandoning Your Own
Being dependable is a valuable quality. It shows compassion, loyalty, and a willingness to support others during difficult times.
But dependability should not require financial exhaustion.
If every improvement in your income creates another obligation, you may never experience the benefits of your own progress. Your earnings can increase while your savings remain unchanged. Your business can grow while your personal financial security stays fragile.
The answer is not to stop helping people. It is to make helping a deliberate decision rather than an automatic obligation.
Protect your essentials. Plan your generosity. Give your business room to grow. Build savings that can support you when life becomes unpredictable.
Remember this: You can be a blessing to others without becoming the solution to every financial problem they face.
Your future deserves a place in your budget, too.

You must be logged in to post a comment.