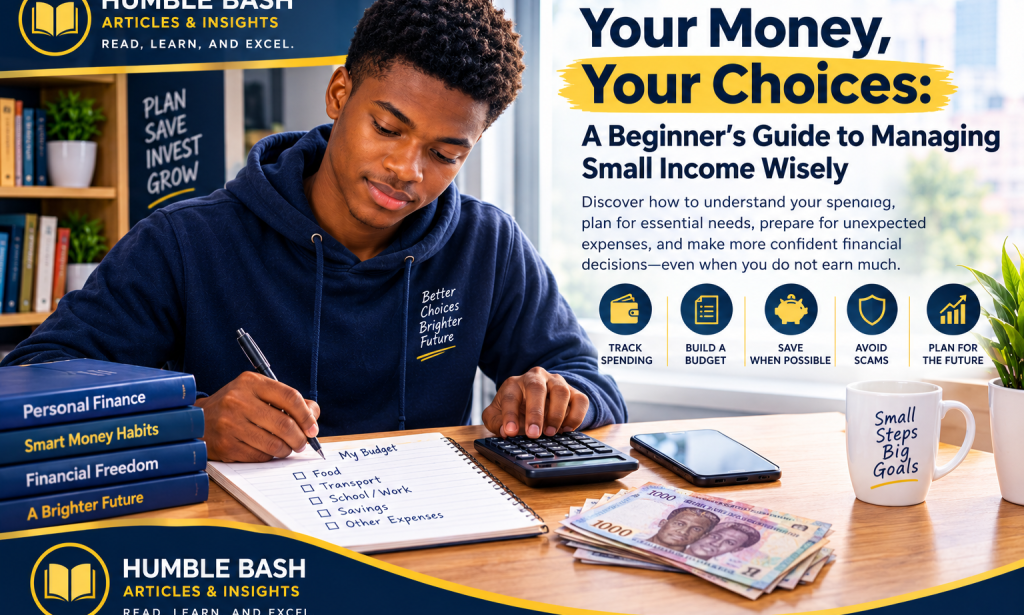
Your Money, Your Choices: A Beginner’s Guide to Managing Small Income Wisely
Introduction: Financial Skills Begin Before You Become Wealthy
Many people believe that managing money becomes important only when they have a well-paying job, a successful business, or a large bank balance. In reality, financial decisions begin much earlier.
A student deciding how to use pocket money, a young person receiving their first payment for a task, and a small business owner managing daily sales all face an important question: how can the money available today support present needs without creating unnecessary difficulties tomorrow?
The answer is not simply to spend less on everything. Some people already struggle to cover essential expenses, and no budgeting technique can magically replace an income that is insufficient. However, understanding where your money goes can help you make informed choices, recognize avoidable costs, and plan more effectively within your circumstances.
Financial literacy begins with awareness. You do not need to know every investment term or have a complicated spreadsheet. You need a clear understanding of your income, responsibilities, spending habits, and priorities.
1. Find Out Where Your Money Actually Goes
The first step toward better money management is observing your spending honestly.
People often remember major purchases but overlook small, repeated expenses. Transport fares, snacks, mobile data, convenience purchases, and service charges can become difficult to track when they are scattered throughout the week.
Try recording your income and expenses for seven days. A notebook or a basic phone note is enough.
For every transaction, write down:
- The amount received or spent.
- What the money was used for.
- Whether the expense was essential, useful, or optional.
At the end of the week, review the list. You may discover that an expense you considered insignificant happens much more frequently than you realized.
The purpose is not to feel guilty about spending. It is to replace guessing with information.
Once you understand your current habits, you can decide which expenses deserve attention and which are reasonable for your situation.
2. Separate Needs, Responsibilities, and Wants
Not every expense has the same level of importance.
Needs are essential items and services, such as basic food, necessary transport, and required school materials. Responsibilities include commitments you have already agreed to meet, such as an important bill or a planned contribution to a household expense. Wants are purchases that may improve your comfort or enjoyment but can often be postponed.
The categories are not identical for everyone. Mobile data, for example, may be essential for someone attending online classes but optional in a different situation.
Before making a purchase, ask yourself three questions:
1. Do I need this now?
2. Have I already committed this money to something important?
3. If I wait, what would I gain or lose?
This short pause can prevent some impulsive purchases.
It does not mean that every enjoyable expense is irresponsible. Entertainment and personal treats can have a place in a realistic budget, provided essential responsibilities are considered first.
3. Build a Budget Around Your Real Income
A budget is a plan for using money, not a punishment for spending it.
Begin with the amount you can reasonably expect to receive. Then list essential expenses and existing commitments. Consider savings only at a level that is realistic after accounting for your needs.
If your income changes from week to week, avoid building your plan around your best week. Use a conservative estimate based on what you can reasonably expect, and adjust when you receive more or less.
For example, someone who earns money from occasional writing assignments might separate each payment into essential expenses, upcoming obligations, and any amount they can safely reserve for future needs.
The proportions will depend on the person's circumstances. A fixed budgeting formula may not work for someone whose income barely covers food and transport.
Review your budget when prices, responsibilities, or income change. A useful budget reflects reality rather than forcing reality to fit an unrealistic plan.
4. Start an Emergency Reserve at a Manageable Pace
Unexpected expenses can disrupt even a carefully prepared budget. A transport problem, urgent household need, or necessary replacement item may require money that was not included in the original plan.
If your circumstances allow it, consider building a small emergency reserve over time.
The first target does not need to be a large amount. You might begin by setting aside a modest sum when you receive income, provided doing so does not prevent you from meeting essential needs.
Keep money intended for emergencies separate from the money you use for everyday purchases, if a safe and practical option is available to you.
Remember that saving is not always possible when income is insufficient. If all available money is required for basic needs, focus first on understanding your expenses and exploring realistic ways to improve your financial position. Avoid blaming yourself for circumstances beyond your control.
5. Learn to Handle Irregular Income
Not everyone receives the same amount of money at regular intervals. Freelancers, casual workers, small traders, and people who earn through occasional tasks may experience periods of higher and lower income.
The challenge is that a good payment can create the impression that more money will always be available.
When a payment arrives, first consider any unpaid obligations and upcoming essential expenses. Then decide what portion, if any, can be reserved for weeks when earnings are lower.
Keep personal spending and business expenses distinct when possible. If you earn money by selling products or providing services, remember that money received is not necessarily profit. Some of it may be needed to cover supplies, transport, or other operating costs.
A simple record of payments received, costs incurred, and money remaining can help you understand the actual result of your work.
Planning around uncertainty is more useful than assuming every month will be equally profitable.
6. Be Careful With Borrowing and Quick-Money Promises
Borrowing can sometimes serve a legitimate purpose, but it creates an obligation to repay. Before accepting a loan, understand the total repayment amount, fees, due dates, consequences of late payment, and the lender's terms.
Do not judge a loan only by the amount offered or how quickly the money becomes available.
Also be cautious about online opportunities promising guaranteed profits, unusually high returns, or effortless income. Pressure to pay an upfront fee, recruit others before receiving earnings, or share sensitive banking details can be warning signs.
Never share your PIN, password, or one-time verification code with someone claiming to help you access money.
If an offer sounds attractive, pause and verify the company or service independently. Discuss uncertain financial decisions with a trusted, knowledgeable person before committing money you cannot afford to lose.
Protecting your money includes knowing when not to take a financial risk.
7. Make Saving and Spending Decisions With a Purpose
Saving becomes easier to understand when you know what the money is for.
You might be saving toward educational materials, a useful tool for your work, transport for an important appointment, or a future expense you can reasonably anticipate.
Give each goal a clear name and an estimated cost. Then decide whether you can contribute regularly or only when money becomes available.
At the same time, recognize that spending on something useful can sometimes be a reasonable decision. Purchasing necessary learning materials or paying for transport to a genuine work opportunity may support your longer-term goals.
The important thing is to consider the purpose, cost, timing, and effect on your other responsibilities before deciding.
Financial maturity is not about refusing to spend. It is about understanding the trade-offs involved.
8. Review Your Financial Situation Every Week
You do not need to spend hours studying your finances. A short weekly review can help you notice changes before they become harder to manage.
Ask yourself:
- How much money came in?
- What were my largest expenses?
- Are any important payments approaching?
- Did I spend money differently from what I planned?
- Is there one adjustment that would help next week?
If the plan did not work, examine why. Perhaps an unexpected expense occurred, your income was lower than expected, or your original estimates were unrealistic.
Use that information to improve the next plan rather than abandoning budgeting altogether.
As your financial situation changes, your approach can change with it.
Conclusion: Start With Awareness, Not Pressure
Managing money wisely does not require wealth, advanced financial knowledge, or a perfect budget. It begins with understanding what comes in, what must go out, and which decisions deserve careful thought.
Track your spending, recognize essential responsibilities, plan around the income you can reasonably expect, and be cautious about borrowing and promises of quick returns. When circumstances allow, build a reserve for unexpected needs and set aside money toward meaningful goals.
Most importantly, remember that financial progress looks different for different people. Someone who can save regularly has different options from someone whose income barely covers basic expenses.
You do not need to compare your financial position with someone else's. Focus on making informed decisions within your circumstances and improving your understanding over time.
Your first financial goal is not to look wealthy. It is to understand your money well enough to make choices that support your needs, responsibilities, and future plans.

You must be logged in to post a comment.