How I Saved a $4,500 Emergency Fund on a $1,800 Monthly Income in 10 Months
Everyone says you should save three months' worth of expenses for emergencies. But how do you achieve that when you earn only $1,800 a month?
I wanted to build an emergency fund, but the goal seemed overwhelming at first. Eventually, I developed a simple savings system that helped me work toward my target without feeling too much pressure.
Here is the approach I followed to build my emergency savings.
My Monthly Expenses Were $1,500
Before I started saving, I calculated how much I spent each month. I wanted to know exactly how much money I needed to cover three months of essential living expenses.
| Expense | Monthly Cost |
|---|---|
| Rent | $700 |
| Food | $250 |
| Transportation | $150 |
| Bills | $200 |
| Other expenses | $200 |
| Total Monthly Expenses | $1,500 |
My monthly income was $1,800, while my expenses were $1,500. That left me with approximately $300 each month before accounting for unexpected costs.
Based on my expenses, I calculated my three-month emergency fund target:
$1,500 × 3 = $4,500
Saving $4,500 seemed like a big challenge, but I decided to break the goal into smaller steps.
Step 1: I Opened a Separate Savings Account
The first thing I did was open a separate savings account. I wanted to keep my emergency money away from the account I used for everyday spending.
I named the account "EMERGENCY ONLY" to remind myself what the money was for.
I also arranged an automatic transfer of $15 every Monday. It was a small amount, but it helped me develop a consistent savings habit.
Saving $15 every week would give me approximately $60 per month when using a four-week estimate.
The advantage of automatic transfers is that I didn't have to remember to save every time I received money. The process became part of my routine.
If your income is limited, you can start with $5, $10, or another amount that fits your budget. The goal is to build a habit without neglecting essential expenses.
Step 2: I Modified the 50/30/20 Budgeting Rule
The traditional 50/30/20 budgeting rule divides your income into three categories:
- 50% for needs: Housing, food, transportation, and essential bills.
- 30% for wants: Entertainment, shopping, and other non-essential purchases.
- 20% for savings: Emergency funds and other financial goals.
Because my income was limited, I decided to use a modified version: 60% for needs, 20% for wants, and 20% for savings.
With a monthly income of $1,800, that would look like this:
| Category | Percentage | Amount |
|---|---|---|
| Needs | 60% | $1,080 |
| Wants | 20% | $360 |
| Savings | 20% | $360 |
| Total | 100% | $1,800 |
I aimed to save $360 monthly, combining automatic transfers with additional deposits when my budget allowed.
However, there was one important challenge: my listed expenses already totalled $1,500, leaving only $300 from my $1,800 income. Therefore, saving $360 every month would require reducing expenses, increasing income, or using additional money from other sources.
The lesson: Choose a savings target that matches your actual budget. A budgeting rule is a guide, not a requirement to save money you cannot afford to set aside.
Step 3: I Put Unexpected Money Into My Emergency Fund
Whenever I received extra money, I tried to put as much of it as possible into my emergency savings instead of immediately spending it.
Some examples of extra money that can help build an emergency fund include:
- Tax refund: A refund of $450 could give your savings a significant boost.
- Birthday money: Saving a $100 gift can move you closer to your target.
- Selling unused items: Selling an old phone or other belongings could provide an additional $200.
- Overtime pay: An extra $150 could go toward your emergency fund.
These are examples rather than guaranteed sources of extra money. Your opportunities will depend on your circumstances.
The principle is simple: when you receive money outside your normal budget, consider putting some or all of it toward your emergency fund before increasing your spending.
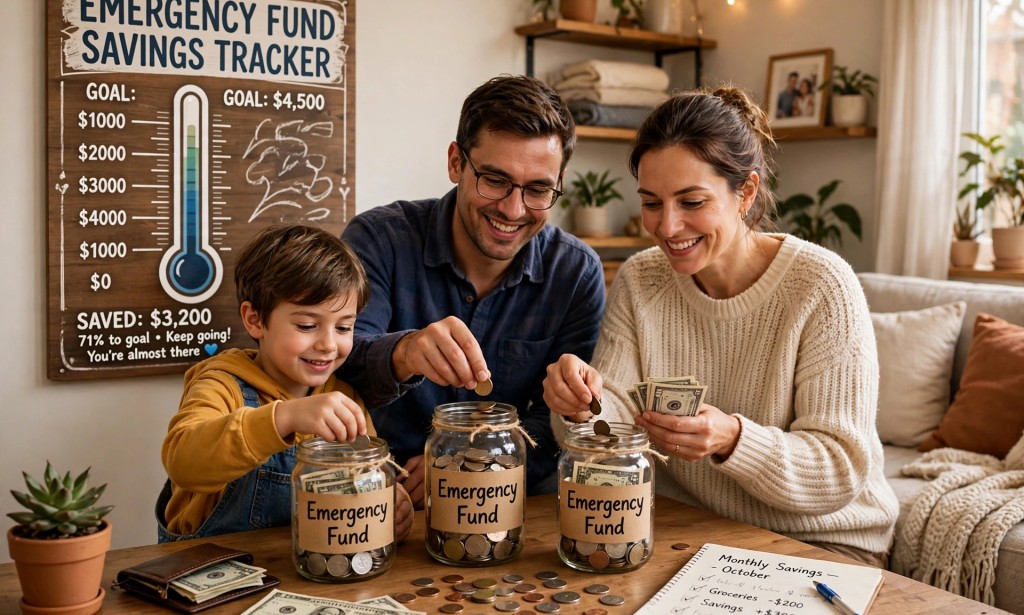
Step 4: I Created a Visual Savings Tracker
Saving money can feel slow when you only look at the final target. To stay motivated, I created a visual tracker showing my progress from $0 to $4,500.
I drew a large thermometer on a piece of paper and marked the savings goal in $100 increments. Every time I saved another $100, I coloured in part of the thermometer.
My children joined in by helping colour the tracker. We also celebrated certain milestones with a small treat, such as ice cream, while keeping the celebration within our budget.
This simple activity made saving feel more rewarding because we could see our progress instead of focusing only on how much money remained.
You can create your own tracker in a notebook, on a whiteboard, or with a free budgeting app. Choose whichever method makes it easier for you to stay consistent.
How My Emergency Fund Grew Over 10 Months
My goal was to build an emergency fund of $4,500. Here is an example of how savings milestones might look along the way:
| Time | Savings Milestone |
|---|---|
| Month 1 | $400 |
| Month 3 | $1,200 |
| Month 6 | $2,600 |
| Month 10 | $4,500 |
These milestones illustrate the target, but the amounts would require additional contributions beyond saving $300 from monthly income alone. The exact timeline depends on how much you can save, whether you receive extra income, and whether unexpected expenses interrupt your progress.
Don't feel discouraged if your progress is slower. Your emergency fund is personal, and your timeline should reflect your actual financial situation.
Why an Emergency Fund Matters
Imagine that you have spent months building your savings when your car suddenly breaks down and needs an $800 repair.
Without emergency savings, you might have to borrow money, use a credit card, or delay the repair. With an emergency fund, you may be able to cover the expense without taking on new debt.
That is the purpose of emergency savings: to help you handle unexpected expenses without completely disrupting your finances.
After using your emergency fund, make rebuilding it part of your financial plan. Remember that the money is there to protect you during difficult situations, not to remain untouched at all costs.
What If You Cannot Save $300 Every Month?
If your income barely covers your essential expenses, saving hundreds of dollars each month may not be realistic. That does not mean you should give up.
Here are a few practical alternatives:
- Start with a smaller target: Aim for your first $100 or $250 before moving toward a larger goal.
- Review recurring expenses: Look for subscriptions, fees, or other costs you can reduce.
- Save when you can: If a particular month is difficult, reduce your contribution rather than missing essential payments.
- Consider additional income: If practical, explore part-time work, freelancing, or selling unused belongings.
- Keep emergency money accessible: Choose a suitable account that allows you to access the money when a genuine emergency occurs.
You do not have to build a three-month emergency fund immediately. Start with a manageable amount and increase your target over time.
Final Thoughts: Start Building Your Emergency Fund Today
Building an emergency fund is not about being rich. It is about preparing for unexpected situations and giving yourself more financial security.
You can begin by tracking your expenses, opening a separate savings account, setting a realistic savings target, and putting extra money aside whenever possible.
Even if you can only save $10 this week, that is a starting point. As your financial situation improves, you can gradually increase your contributions.
Your future self may thank you for preparing today. Start small, stay consistent, and build your emergency fund at a pace you can afford.
What About You?
Do you already have an emergency fund, or are you still working toward your first $1,000 in savings?
Share your savings tips or challenges in the comments. Your experience could help someone else take the first step toward financial security.
Disclaimer: This article is for educational purposes only. The figures are illustrative and may not reflect everyone's income, expenses, or savings experience. Adjust any budgeting approach to suit your circumstances.

You must be logged in to post a comment.